Contractor Insurance Documents for Connecticut Real Estate Investors: Certificates, Additional Insureds, Waivers, Limits, and Contract Review
See How We're Different
or call us: (888) 585-5188

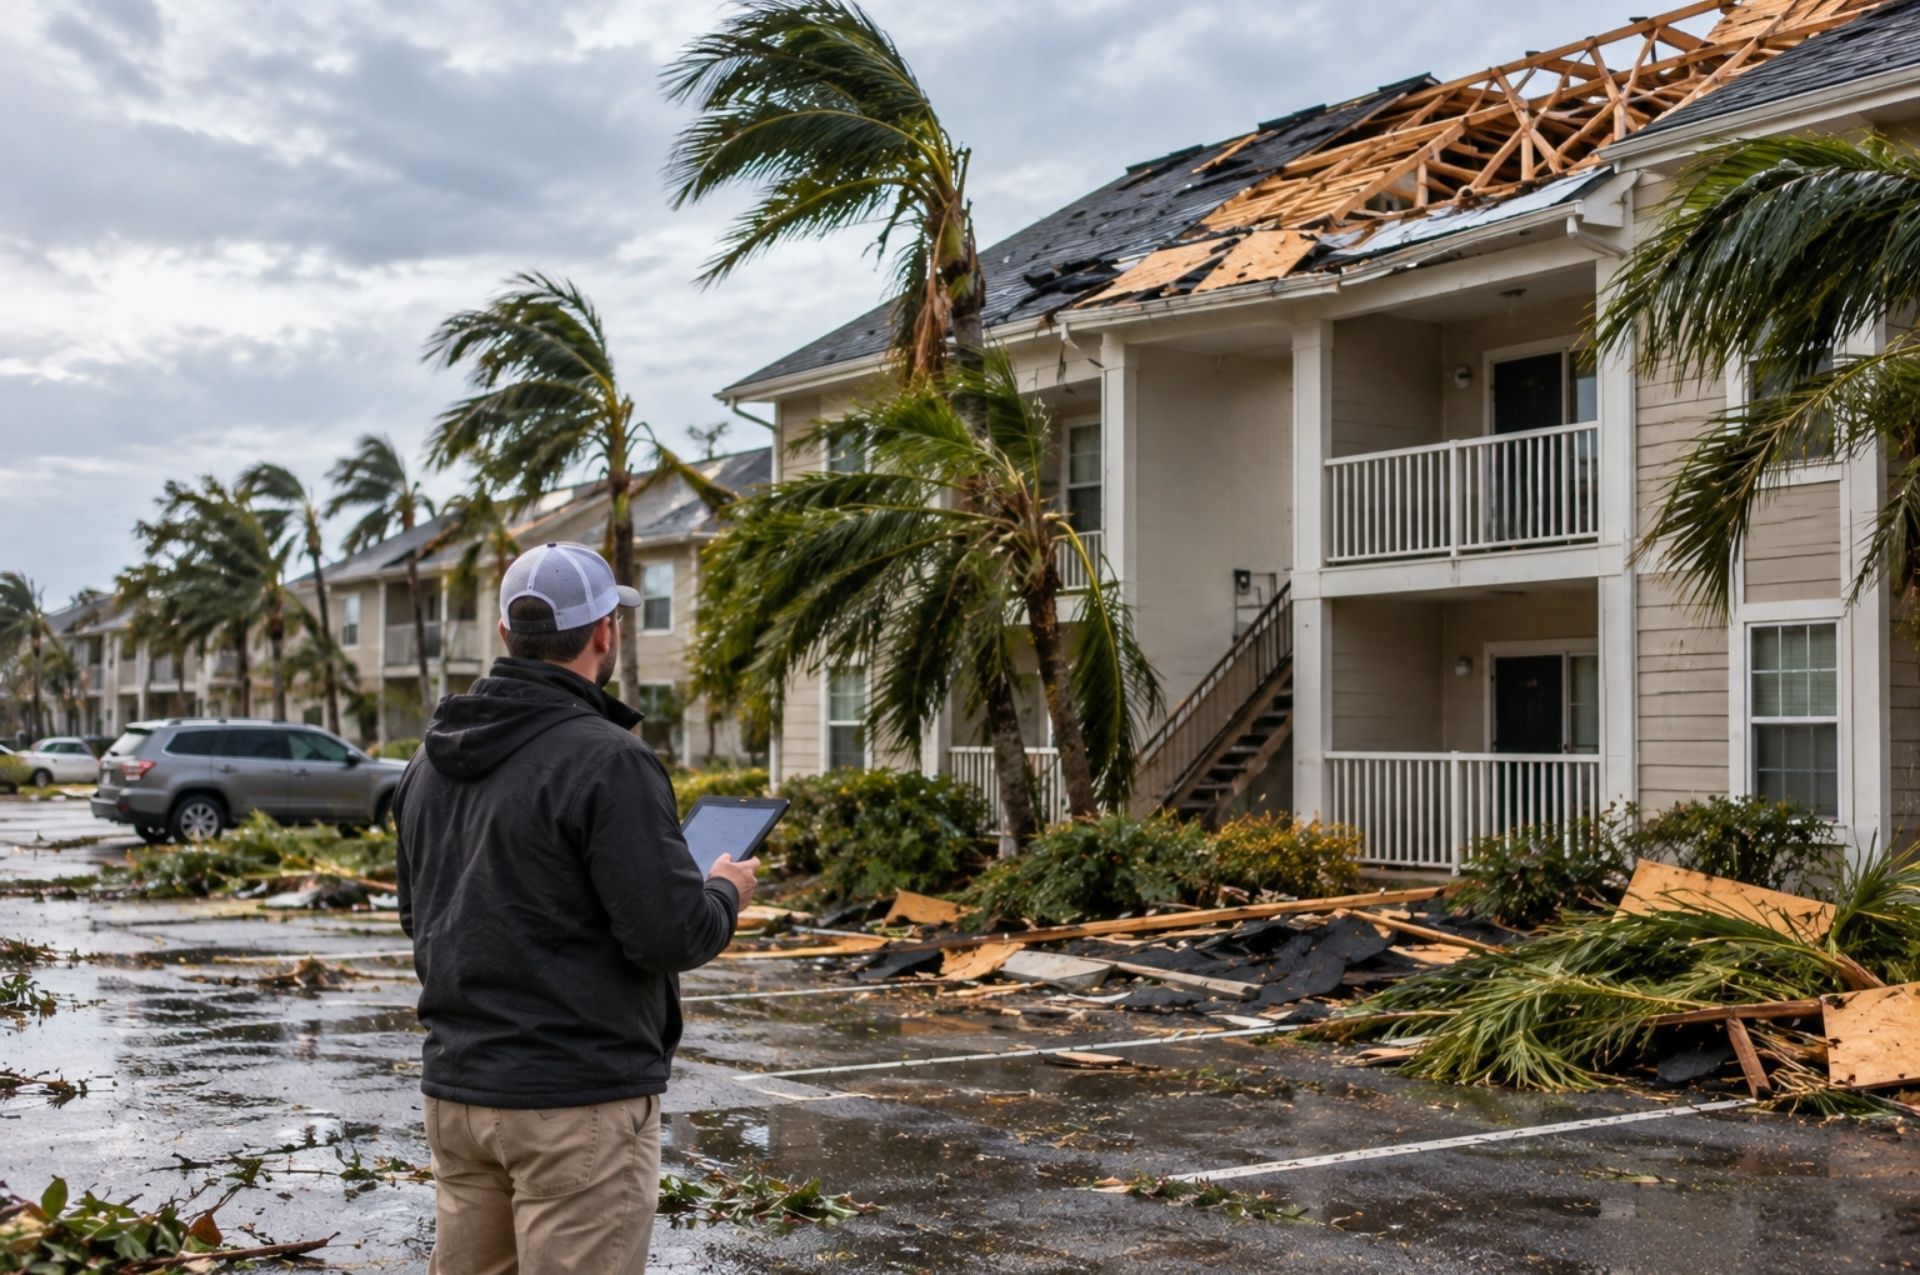
Picture a Connecticut investor three weeks into a gut renovation of a two-family home in New Haven when a roofer's helper falls through a skylight opening. The general contractor's policy was cancelled for non-payment a month earlier, and the certificate in the investor's file is out of date. Situations like this are why contractor insurance documents for Connecticut real estate investors deserve the same scrutiny as a title report or an appraisal.
Certificates, additional insured endorsements, waivers, coverage limits, and contract language work together as a single system of protection. When one piece is missing or poorly worded, the entire structure can fail at the moment it is needed most. The guidance below explains what each document does, where gaps typically appear, and how to review them before work begins.
The Role of Insurance Documentation in Connecticut Real Estate
Insurance documentation is the written proof that a contractor's risk will not become the property owner's financial burden. For investors, the stakes are higher than they are for a typical homeowner. Rental properties, flips, and multifamily buildings often involve multiple trades on site at once, tenants or neighbors nearby, and lenders who require evidence of proper coverage before releasing draws.
Connecticut adds its own layer of regulation. Contractors performing residential work must hold Home Improvement Contractor registration, and the state requires a minimum of $20,000 in general liability insurance to maintain that registration. That figure is a licensing floor, not a recommended level of protection for an investment property. A single bodily injury claim involving a fall from a ladder can exceed that amount within days of medical treatment.
Owner exposure also extends past the contractor's own work. Under Connecticut
premises liability principles,
an injured worker or visitor may name the property owner in a lawsuit, and the documents in the investor's file determine whether the contractor's insurer steps in to defend that claim. Without them, the investor's own property policy, which may already be under pressure from rising Connecticut premiums, absorbs the loss.
Mastering the Certificate of Insurance (COI)
The certificate of insurance, usually issued on an ACORD 25 form, is a one-page summary of a contractor's policies. It lists the insurers, policy numbers, effective dates, and limits for general liability, auto liability, umbrella coverage, and workers' compensation. That said, the certificate itself confers no rights. It is an informational snapshot that can become inaccurate the day after it is issued.
Investors should always request the certificate directly from the contractor's insurance agent rather than accepting a PDF forwarded by the contractor. Agent-issued certificates are far harder to alter, and the agent can confirm that the policy is active. Recent Connecticut case law shows why this matters: the Appellate Court upheld a rapid default judgment against a contractor for unpaid premiums, a reminder that policies can lapse mid-project when contractors fall behind on payments.
Verifying General Liability and Workers' Comp Limits
General liability limits are typically shown as a per-occurrence figure and a general aggregate. Investors should confirm both, and should check whether the aggregate applies per project or across all of the contractor's jobs. A contractor working on twenty sites with a shared aggregate may have already exhausted much of that limit before reaching the investor's property.
Workers' compensation deserves equal attention. A contractor who claims to have no employees may present a certificate showing no workers' comp coverage, yet still bring helpers to the site. If one of those helpers is injured, the claim can move up the chain toward the general contractor and, in some circumstances, the owner. Requesting written confirmation of crew size and any sole proprietor exemption filings closes that gap.
Additional Insured Status and Why It Matters
Additional insured status extends the contractor's liability policy to protect the property owner for claims arising from the contractor's work. A checked box on the certificate is not enough. The investor needs the actual endorsement, commonly ISO forms CG 20 10 for ongoing operations and CG 20 37 for completed operations.
Completed operations coverage is the piece most often missing. A deck that collapses eighteen months after construction, injuring a tenant, falls under completed operations, and an endorsement limited to ongoing work will not respond. Investors should also request primary and non-contributory wording so the contractor's policy pays before the investor's own coverage is touched.
Waivers of Subrogation and Indemnity Clauses
A waiver of subrogation prevents the contractor's insurer from pursuing the property owner after paying a claim. Without it, the insurer that covers an injured worker could seek reimbursement from the owner by arguing that a site condition contributed to the accident. Waivers should appear both in the contract and as an endorsement on the general liability and workers' compensation policies, because a contract promise alone does not bind the insurer.
Indemnity clauses require one party to cover the other's losses, and Connecticut places firm limits on them. State law voids construction contract provisions that indemnify a party for its own negligence, so an investor cannot shift responsibility for an injury that the investor caused. A well-drafted clause instead asks the contractor to indemnify the owner to the extent the loss arises from the contractor's work or negligence.
One common mistake is copying a broad indemnity form from another state. In Connecticut, an overreaching clause risks being struck down, leaving the investor with less protection than a narrower, enforceable version would have provided.
Comparison of Standard vs. Enhanced Coverage Requirements
Many investors simply accept whatever coverage a contractor already carries. The table below contrasts that minimum approach with the requirements a careful investor typically writes into a contract. Specific dollar limits should be set with an insurance advisor based on project size, property type, and lender requirements.
| Requirement | Standard (Minimum) | Enhanced (Investor-Grade) |
|---|---|---|
| General liability | State HIC floor of $20,000 | Limits sized to project value and exposure |
| Aggregate | Shared across all jobs | Per-project aggregate endorsement |
| Additional insured | Box checked on certificate | CG 20 10 and CG 20 37 endorsements attached |
| Completed operations | Often not addressed | Required for a set period after completion |
| Primary/non-contributory | Not included | Required by endorsement |
| Waiver of subrogation | Absent or contract-only | Endorsed on GL and workers' comp |
| Umbrella/excess | Rarely required | Required for multifamily or structural work |
| Subcontractor coverage | Not verified | Flow-down requirements and COIs for each sub |
The value difference is easiest to see in a claim. Under the standard approach, a tenant injury after completion may land on the investor's own policy. Under the enhanced approach, the contractor's insurer defends and pays first.
Best Practices for Reviewing Contractor Contracts
Contract review is where insurance protection is either secured or lost. A thorough review of these agreements should confirm that every coverage requirement is stated clearly, tied to specific endorsements, and backed by consequences for non-compliance, such as withholding payment until updated certificates arrive.
Aligning Contract Terms with Insurance Policies
The contract and the policy must say the same thing. If the agreement requires completed operations coverage for three years but the endorsement only covers ongoing operations, the contract promise is worth little in a claim. Investors should compare each insurance clause against the actual endorsement language before signing.
A practical approach is to attach the required endorsement forms as an exhibit to the contract. The contract should also require thirty days' written notice of cancellation and updated certificates at each policy renewal, so that a lapse does not go unnoticed.
Common Red Flags in Connecticut Subcontractor Agreements
Several warning signs appear repeatedly in Connecticut agreements:
- Deductible offsets: Under HB 5263, contractors are prohibited from offering to pay or offset a homeowner's insurance deductible as an inducement to sign. An offer like this signals a contractor willing to cut corners.
- Wage liability waivers: Starting January 1, 2027, general contractors become jointly and severally liable for unpaid wages owed by subcontractors at any tier. Any clause claiming to waive that liability is unenforceable and suggests an outdated template.
- Missing flow-down language: Subcontractors who are not required to carry matching coverage leave gaps beneath the general contractor.
- Self-insured retentions: Large retentions mean the contractor pays early losses directly, which may never happen if the business is undercapitalized.
Common Questions About Contractor Insurance
Is a certificate of insurance enough to protect me? No. A certificate only summarizes coverage and grants no rights, so investors should obtain the actual additional insured endorsement.
How often should I ask for a new COI? Request one before work begins, at every policy renewal date, and any time the contractor changes insurers. Long projects often outlast a policy term.
What happens if a contractor's policy is cancelled mid-project? Claims arising after cancellation may not be covered, leaving the investor's property policy exposed. Requiring notice of cancellation and halting work until coverage is restored reduces this risk.
Do I need to check subcontractors' insurance too? Yes. Each subcontractor should provide its own certificate and endorsements, since the general contractor's policy may exclude work performed by uninsured subs.
Can my contract make the contractor responsible for everything?
Not in Connecticut. State law voids indemnity for the owner's own negligence, so clauses should focus on losses caused by the contractor's work.
Your Next Steps for Risk Management
Strong protection for an investment property comes from treating these documents as a connected system: verified certificates, proper additional insured endorsements, endorsed waivers, adequate limits, and contract language that matches the policies. Applying these contractor insurance tips before the first invoice is paid prevents most of the disputes that later reach adjusters and courtrooms.
Start by building a standard insurance exhibit for every contract, listing the required limits and endorsement forms. Then set calendar reminders for each contractor's renewal dates, and keep a file of current certificates for every trade on each property. Finally, ask an experienced insurance advisor to review the first few contracts and endorsements so that the template reflects current Connecticut law, including the 2027 wage liability changes.
The paperwork may feel tedious during a fast-moving renovation. A single uncovered claim, however, can erase the profit from an entire project, which makes careful documentation one of the most valuable habits any Connecticut investor can develop.
Recent posts