Lessor's Risk Insurance for Multi-Family Portfolios
or call us: (888) 585-5188
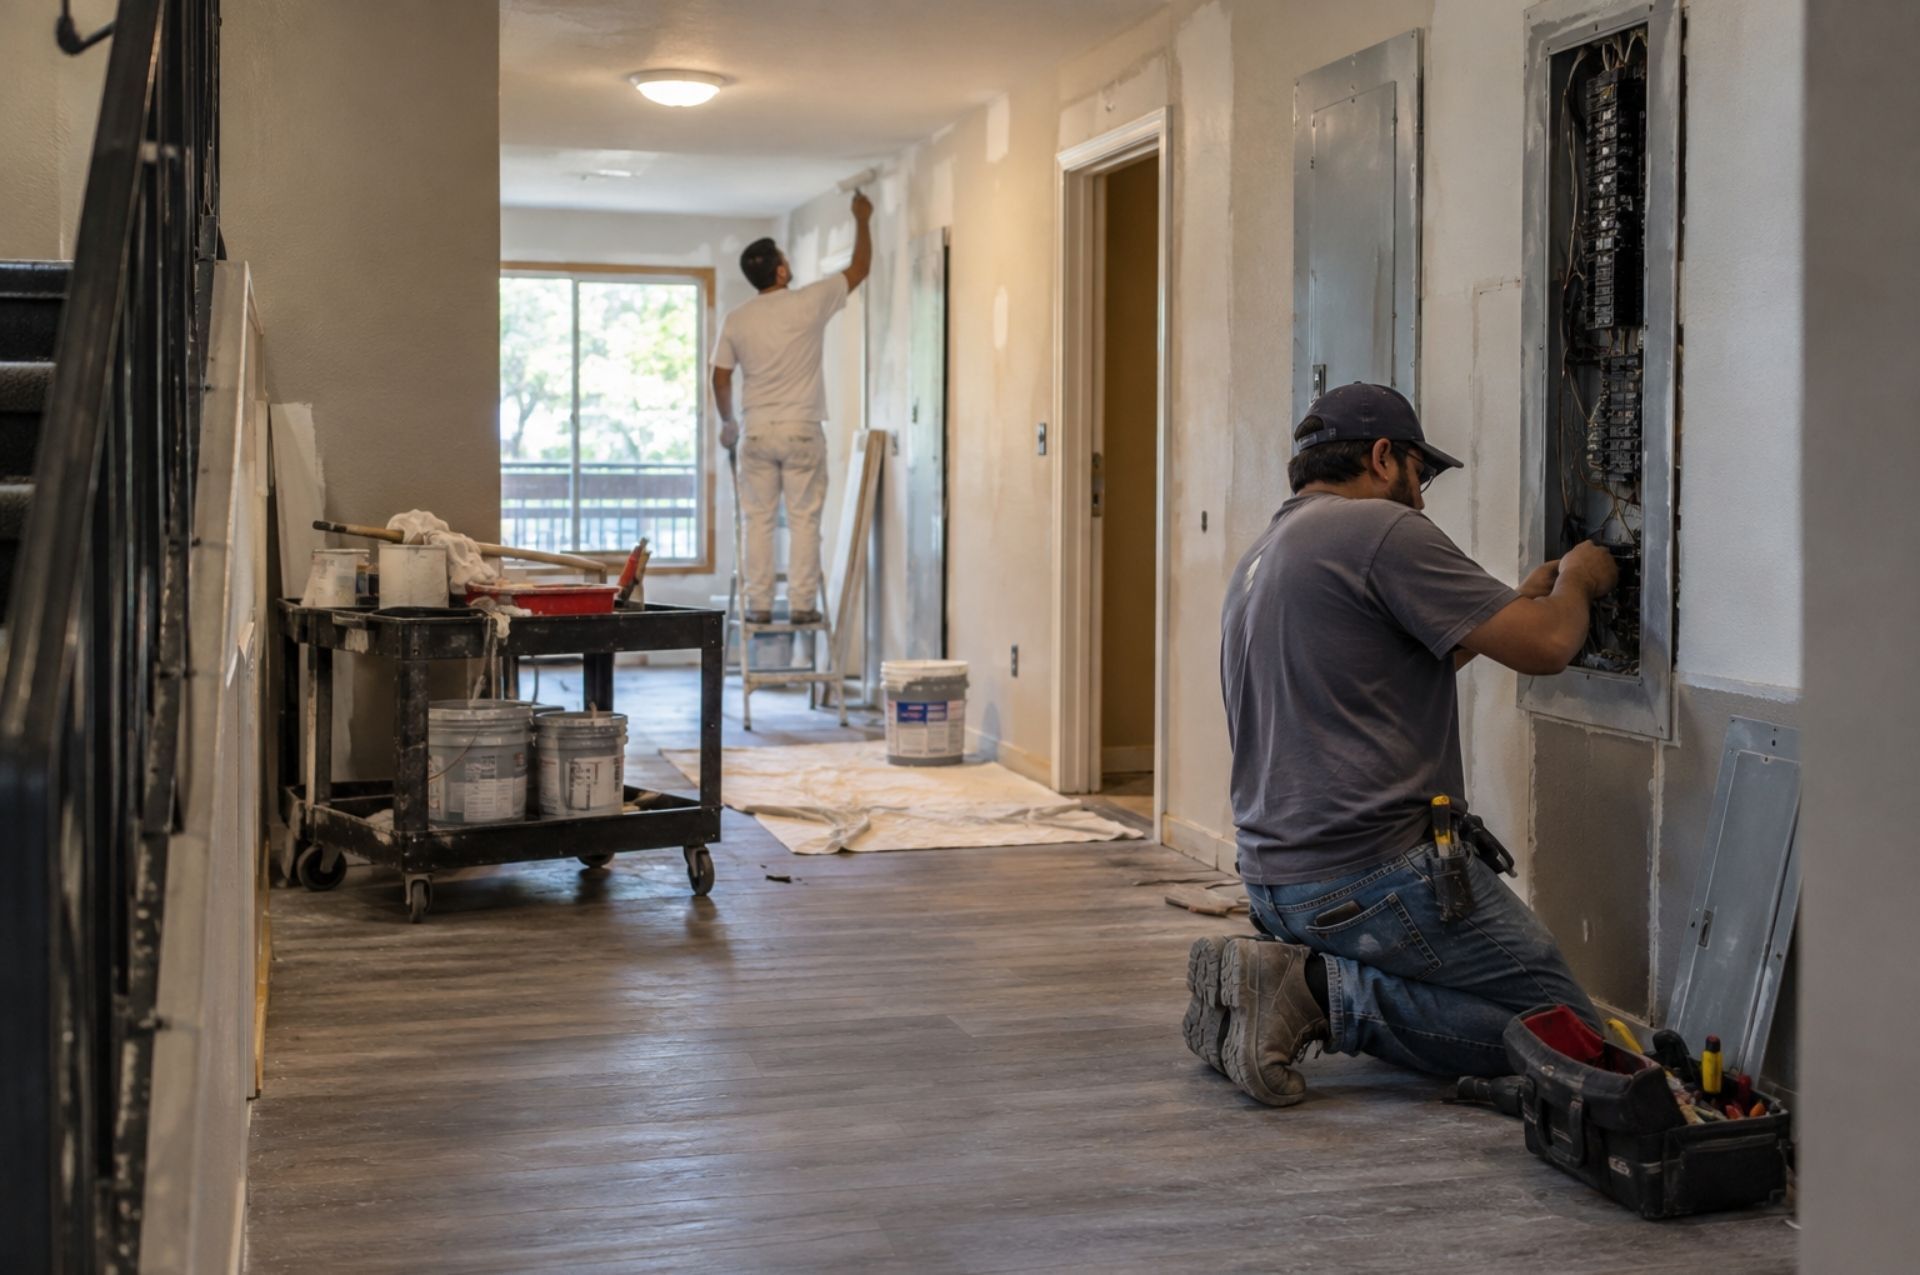
Owning a small portfolio of rental duplexes, triplexes, or fourplexes creates a distinct set of insurance challenges that fall between a single-family landlord policy and a large commercial program. A standard homeowners policy will not respond when a property is tenant-occupied, yet a full commercial package may carry more complexity and cost than the portfolio warrants. Lessor's risk insurance, often abbreviated LRO, fills that gap by bundling property coverage, premises liability, loss of rent protection, and umbrella options into a single program designed for non-owner-occupied residential buildings. For landlords holding one-to-four-family properties, understanding how these coverages interact, and what tenant requirements should accompany them, is the difference between a well-protected portfolio and a single claim that erases years of cash flow. The good news is that commercial and landlord property insurance rates have
begun to soften in early 2026 after five consecutive years of increases, giving portfolio owners a window to reassess their coverage at more competitive premiums.
Understanding Lessor's Risk Only (LRO) for Multi-Family Owners
A lessor's risk only policy is purpose-built for property owners who do not occupy the insured buildings. Unlike policies written for owner-occupants, an LRO form acknowledges from the outset that the insured has no control over the day-to-day activities inside each unit. The policy therefore focuses on the structure, common areas, and the landlord's legal liability rather than on tenant belongings or tenant-caused losses. For owners of duplexes through fourplexes, this distinction matters because the policy is priced and underwritten around rental exposure, not homeowner exposure.
Core Protections: Liability and Property Damage
At its foundation, an LRO policy pairs two essential coverages. The property component insures the building itself, including roofing, HVAC systems, plumbing, and permanently installed fixtures, against named perils or, in broader forms, against all risks not specifically excluded. The liability component responds when a third party, whether a tenant, a guest, or a delivery driver, suffers bodily injury or property damage on the premises due to a condition the landlord is responsible for maintaining. A cracked sidewalk, a collapsed porch railing, or a malfunctioning fire escape are classic examples of claims that fall squarely within this coverage.
Why Standard Homeowners Policies Aren't Enough
A homeowners policy, such as an HO-3 or HO-5, contains an explicit business-pursuits exclusion. The moment a property is rented to a tenant for income, the insurer can deny a claim on the grounds that the loss arose from a business activity. Some carriers offer a landlord endorsement on a homeowners form, but these endorsements typically cap liability at low limits and exclude loss of rent entirely. Portfolio owners who rely on homeowners policies across multiple properties are carrying uninsured exposure on every building, often without realizing it until a claim is filed and denied.
Key Coverages for Diverse Property Portfolios
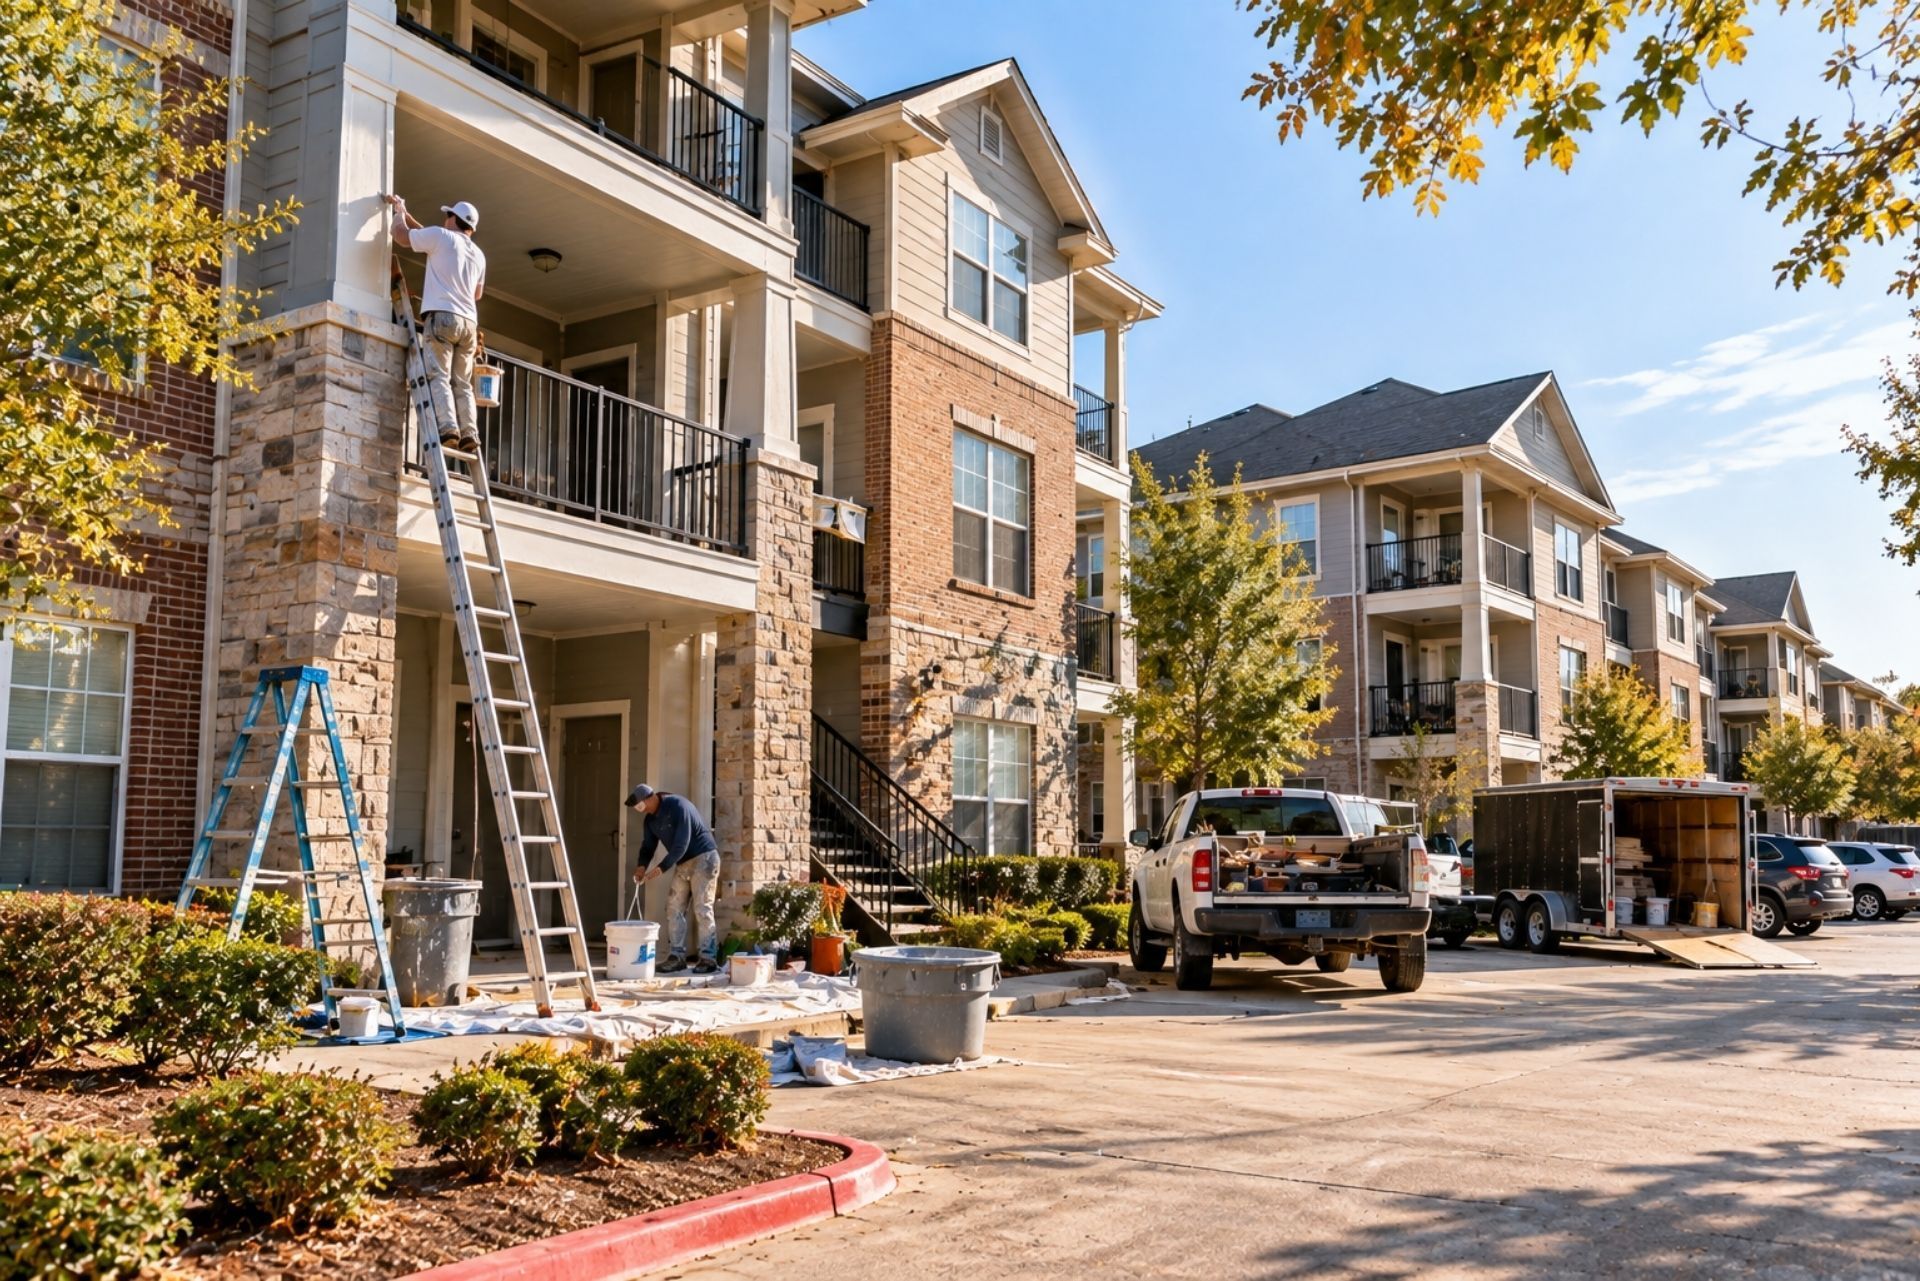
A well-structured LRO program for one-to-four-family portfolios bundles several coverage lines that address the specific risks landlords face. Each coverage responds to a different loss scenario, and gaps between them are where financial damage occurs.
General Liability for Tenant and Guest Injuries
Premises liability is the coverage most landlords think of first, and for good reason. A slip-and-fall on an icy common walkway or a dog bite in a shared yard can generate medical bills and legal fees that quickly exceed six figures. General liability within an LRO policy typically starts at $1 million per occurrence with a $2 million aggregate, though portfolio owners with higher-value properties or buildings in litigious jurisdictions often carry $2 million per occurrence. The policy also covers the cost of legal defense, which is paid outside the liability limit in most forms, a detail that significantly increases the effective protection.
Business Income Protection and Loss of Rents
If a covered peril, such as a fire or burst pipe, renders a unit uninhabitable, loss of rent coverage replaces the rental income the landlord would have collected during the restoration period. Insurance experts recommend that landlords reprice loss-of-rent coverage based on actual local re-leasing timelines rather than accepting a generic 12-month indemnity period, which may be longer or shorter than the real vacancy exposure. A fourplex in a market where units lease within 45 days needs a different indemnity period than one in a rural area where vacancies stretch to six months.
Equipment Breakdown and Utility Interruption
Boilers, central air conditioning compressors, and commercial-grade water heaters are not always covered under a standard property form because they fail due to mechanical or electrical breakdown rather than a named peril. An equipment breakdown endorsement closes this gap and can also cover spoilage losses if a freezer or refrigerator in a common area fails. Utility interruption coverage, sometimes bundled with equipment breakdown, responds when an off-premises utility failure causes a loss at the insured property.
Comparison: Basic vs. Comprehensive LRO Coverage
The table below highlights the practical differences between a stripped-down LRO policy and a comprehensive program. Most portfolio owners find that the incremental premium for comprehensive coverage is modest relative to the additional protection.
| Coverage Feature | Basic LRO | Comprehensive LRO |
|---|---|---|
| Named-peril property | Included | Replaced by open-peril form |
| Premises liability | $1M / $2M | $2M / $4M or higher |
| Loss of rent | Repriced by local timeline | Repriced by local timeline |
| Equipment breakdown | Excluded | Included by endorsement |
| Ordinance or law | Excluded or 10% sub-limit | 10%-25% of building limit |
| Umbrella eligible | Rarely | Yes, scheduled across portfolio |
| Water backup | Sub-limited or excluded | Full sub-limit available |
An umbrella policy layered above the comprehensive form is particularly valuable for multi-property owners because a single serious liability event at one building can threaten the equity in every other property the landlord owns. Umbrella limits of $2 million to $5 million are common for portfolios of four to ten units.
Managing Risk Across Multiple Locations
Owning properties at different addresses, possibly in different municipalities or even different states, introduces administrative and underwriting complexity that a single-property landlord never encounters.
The Benefits of a Master Policy Structure
A master policy consolidates all insured locations under one policy number, one renewal date, and one set of terms. This structure eliminates coverage gaps that arise when individual policies renew on different dates or carry inconsistent exclusions. Consolidating rental properties under a single master policy typically generates savings of around 25% compared to insuring each property separately. The savings come from reduced administrative overhead for the carrier and a larger total insured value that spreads catastrophic risk.
Navigating Occupancy Requirements and Vacancy Clauses
Most LRO policies contain a vacancy clause that restricts or eliminates coverage if a building falls below a specified occupancy threshold, often 31% vacant for more than 60 consecutive days. [https://www.irmi.com/articles/expert-commentary/vacancy-what-does-it-mean-for-commercial-property-coverage] [https://www.fronteraclaims.com/field-guide/vacancy-clause] For a fourplex, losing two tenants simultaneously does not trigger this clause as 50% occupancy remains above the threshold. [https://www.irmi.com/articles/expert-commentary/vacancy-what-does-it-mean-for-commercial-property-coverage] Portfolio owners should negotiate vacancy provisions at binding, not after a loss. Some carriers offer a vacancy permit endorsement that suspends the clause for a stated period, and others will modify the threshold percentage for an additional premium. [https://www.fronteraclaims.com/field-guide/vacancy-clause]
Seasonal markets present a particular challenge. A duplex in a college town may sit empty every summer, and the standard vacancy clause could leave the owner without vandalism or water-damage coverage during those months. Disclosing the seasonal pattern to the underwriter at the application stage is the most reliable way to secure appropriate terms.
Frequently Asked Questions
Does LRO cover damage caused by my tenants? Generally, no. An LRO policy covers damage from insured perils like fire, wind, or water, but intentional or negligent damage by a tenant is typically excluded or subject to subrogation. The landlord can file a claim for the peril itself, such as a fire, but the carrier may then pursue the tenant for reimbursement.
How many units do I need to qualify for a multi-family policy? Most carriers write LRO policies starting at a single duplex. The "multi-family" classification usually begins at two units in one building. Portfolios of mixed property types, such as a duplex and two single-family rentals, can often be combined on one policy through a master program.
Do I still need my tenants to have their own insurance? Yes. An LRO policy does not cover tenant personal property or tenant liability. Requiring renters insurance in the lease is a best practice, though only 55% to 57% of renters nationally maintain active coverage, which means landlords should verify compliance regularly, not just at lease signing.
Will this policy cover me if a building is partially empty? It depends on the vacancy clause. If occupancy drops below the policy threshold for more than the stated period, coverage for certain perils like vandalism and water damage may be suspended. A vacancy permit endorsement can extend protection during transitional periods.
What is the difference between LRO and a standard commercial policy? An LRO policy is a subset of commercial property insurance tailored for non-owner-occupied residential buildings. A standard commercial policy may include coverage for business operations conducted on-site, employee liability, and product liability, none of which apply to a passive rental operation. LRO is leaner, less expensive, and specifically designed for the landlord's exposure profile.
Making the Right Choice for Your Portfolio
Selecting the right lessor's risk insurance program for a one-to-four-family portfolio requires matching the coverage structure to the actual risk each property presents. A basic named-peril policy might suffice for a single duplex in a low-risk area, but a portfolio spread across several locations, especially one that includes older buildings or properties in flood-prone zones, demands broader terms, higher liability limits, and an umbrella layer.
The 2026 market offers favorable conditions for this reassessment. Multifamily insurance cost benchmarks have settled at approximately $600 per door for Class A and B-plus properties and $700 to $800 per door for Class B and C properties, giving portfolio owners a concrete starting point for budgeting. Landlords who combine a comprehensive LRO form with a master policy structure, enforce tenant insurance requirements, and review vacancy clauses annually will carry far less uninsured exposure than those who treat insurance as a set-it-and-forget-it expense. Start by requesting quotes that itemize each coverage component separately so the cost of every protection, and the cost of skipping it, is visible before a binding decision is made.
About The Author:
Anton Reed
As Managing Principal of Adion Financial Group, I’m committed to helping individuals and businesses achieve financial security through strategic insurance and planning solutions. My focus is on building trust, delivering clarity, and ensuring every client receives expert guidance backed by experience and integrity.
Contact Us
Personal INSURANCE Coverage
Comprehensive Coverage for Every Personal Need
Business Insurance Solutions
Professional Liability Coverage for Service-Based Businesses
General Liability Insurance
Protects businesses from lawsuits related to injuries and property damage.
INDUSTRIES WE SERVE
Specialized Coverage for Leading Connecticut Industries
Contractors
Insurance
Whether you’re a general contractor or a specialized tradesperson, we offer coverage that protects against job site risks, equipment damage, and liability claims.
Commercial Truck Insurance
Whether you operate a single truck or an entire fleet, we provide coverage for cargo, liability, and physical damage to keep your business moving.
Restaurant Business Insurance
Keep your restaurant, café, or bar protected with coverage for property damage, liquor liability, foodborne illness, and employee injuries.
Commercial Real Estate Insurance
Safeguard your commercial properties, rental units, and office spaces from property damage, liability claims, and tenant-related risks.
“I’ve been with AFG for years. Their service is second to none, and I always feel confident that I’m covered.”
Sarah K.
Real Stories.
Real Protection.
Real Trust.
See Why Businesses and Families Trust Us for Coverage.
Quick Answers to Your Insurance Questions
Frequently Asked Questions
about Adion Financial Group
Understanding Insurance Starts with the Right Information
1. What types of insurance do you offer?
At Adion Financial Group, we offer a wide range of insurance options designed to meet the needs of both individuals and businesses. For individuals, we provide coverage for personal auto, home, renters, life, and health insurance. Whether you're looking to protect your home, your car, or your loved ones, we have a solution tailored to your needs.
2. How do I get a quote for insurance?
Getting an insurance quote with Adion Financial Group is simple and fast. First, visit our website and fill out the quote request form, providing some basic information about the type of insurance you need. If you prefer a more personal touch, you can also contact us directly, and one of our agents will walk you through the process.
3. What should I do if I need to file a claim?
If you need to file a claim, the first step is to notify us immediately. You can either call our office or submit your claim online, depending on your preference. Once we receive your claim, our team will guide you through the necessary steps and help you gather the required information.
4. How can I change my coverage or update my policy?
Making changes to your coverage or updating your policy is easy with Adion Financial Group. Whether you're moving to a new home, adding a vehicle, or expanding your business, we can help you adjust your insurance to reflect your current needs.
5. Why should I choose an independent insurance agency?
Choosing an independent insurance agency like Adion Financial Group provides you with a distinct advantage: we work for you, not an insurance company. Our independent status allows us to shop around with multiple carriers to find the most competitive rates and the best coverage options for your unique situation.
6. How can I make sure I have the right amount of coverage?
Determining the right amount of coverage can be overwhelming, but our team at Adion Financial Group is here to help. The first step is assessing your personal or business assets and identifying the potential risks you face. Whether you're an individual looking to protect your home and car, or a business owner trying to safeguard your employees and property, we will walk you through the different coverage options.
Stay Informed on Insurance Trends and Tips
Insights & Tips to Keep You Informed
Contact Us
Phone
Locations
Connecticut Location
703 Hebron Ave., 3rd Floor, Glastonbury, CT 06033
North Carolina Location
436 East 36th St., Charlotte, NC 28205